Last Step: Book Your Discovery Session to Find Your Best Lending Option
DON'T JUST TAKE OUR WORD FOR IT
What Our Clients Say About Working With Expert Mortgages
Whatever You're Trying to Do,
There's a Path
Investment Lending
Structure your loans right and you can keep buying, instead of getting stuck after property one.
Commercial Lending
Get funding that actually understands how your business makes money, not a rigid one-size-fits-all box.
First Home Buyers
Stop guessing what you can afford — know your number and get pre-approved before you fall in love with a place.
Self-Managed Super Fund
Turn your super into property and take control of your retirement — done properly, compliantly, and without the ATO headaches.
Refinancing
If you haven't switched in 18+ months, you're probably paying more than a new customer would. Let's fix that.
Asset & Equipment Finance
Get the vehicle, gear, or tech your business needs now, without draining your cash reserves to do it.
Bridging Loans
Buy your next place before you sell your current one — no double repayments, no rushed sale.
Separation Finance
Unlock your share of the equity and move forward on your own terms, without waiting months for a sale to settle.
THE STUFF EVERYONE ASKS
Frequently Asked Questions
Is it worth using a mortgage broker in Australia?
For most borrowers, yes. As of the June 2024 quarter, brokers arranged 73.7% of all new home loans in Australia, up from 57% in June 2020 — a strong signal borrowers are finding real value in it. A broker compares products across a panel of lenders instead of just one bank’s range, and is legally required to act in your best interests under Australian credit law. The value is highest when your situation isn’t the simplest vanilla case — self-employed income, multiple properties, refinancing, or anything with a tight timeline.
How do mortgage brokers get paid in Australia?
Brokers are typically paid a commission by the lender once your loan settles — not a fee charged to you directly, in the vast majority of cases. This usually includes an upfront commission and a smaller ongoing “trail” commission for as long as the loan runs. Brokers are legally required to disclose how they’re paid and by whom, so it’s a completely fair question to ask upfront — we’re always happy to walk through it.
Is it cheaper to use a mortgage broker, or does it cost me more?
Using a broker doesn’t cost you more upfront in the overwhelming majority of cases — the broker is paid by the lender, not by you. What it can save you is time (comparing dozens of lenders yourself) and potentially money, since a broker may have access to rates, cashback offers, or loan features you wouldn’t find by walking into a single bank branch.
What’s the downside of using a mortgage broker?
The main thing to check is whether a broker’s lender panel is genuinely broad, or limited to a small group they default to. A good broker will be transparent about their panel size and won’t push you toward a lender purely because the commission is higher. Ask directly how many lenders they compare and whether any are excluded — a broker with nothing to hide will answer plainly.
Is it better to use a mortgage broker or go directly to a bank?
A bank can only offer you their own products. A broker can compare across their panel, which often includes the same major banks plus non-bank and specialist lenders that may suit your situation better. The right choice depends partly on how simple your situation is — but for anything beyond the most straightforward loan, broker access to more options generally works in your favour, at no extra cost to you.
How much does a mortgage broker cost in Australia?
In the large majority of home loan and investment loan scenarios, there’s no direct cost to you — the broker is paid via commission from the lender. Some complex commercial or asset finance arrangements can involve a broker fee disclosed and agreed upfront, but this isn’t the norm for standard residential lending. Always ask for this in writing before proceeding — a reputable broker will provide it without hesitation.
Do I need a 20% deposit to buy a home?
Not necessarily. While a 20% deposit avoids Lenders Mortgage Insurance (LMI), government schemes exist that let eligible first home buyers purchase with a deposit as low as 5%, and in some cases even less. Eligibility and available schemes can change, so it's worth checking your specific situation rather than assuming you need to save the full 20%.
Should I wait for interest rates to drop before buying?
Timing the market perfectly is more luck than strategy — nobody, including the banks, can predict exactly when or if rates will move. A more reliable approach is understanding what you can genuinely afford right now, buying when the right property comes along, and refinancing later if rates do fall. Waiting indefinitely usually just means paying rent while property prices keep moving.
Why does my borrowing power change even if my income hasn't?
Lenders assess your ability to repay a loan using a buffer rate above whatever the current interest rate is, so your borrowing power shifts as rates move — even if nothing in your own finances has changed. This is why a borrowing power figure from a year or two ago might not reflect what you'd actually be approved for today. It's always worth getting a fresh number before you start looking.
I've owned property before — can I still be classed as a first home buyer?
Possibly, yes. Under current government guidelines, you may still qualify for first home buyer schemes and grants even if you've owned property in the past, as long as you haven't held an interest in Australian real estate in the last 10 years. It's worth checking properly rather than assuming you've missed out.
How It Works
We've simplified the mortgage process into three clear stages to turn your financial goals into realities with peace of mind.
Specialist Lender Selection
We begin by understanding your unique story and wealth-building goals, mapping out your borrowing power with precision.
Expert Solution
We compare options from our panel of 40+ lenders to find the smart, tailored lending strategy that best fits your future.
Path to Prosperity
We handle the complex paperwork and management through to settlement, ensuring a clear and empowering transition to your new loan.
MEET YOUR MORTGAGE BROKER
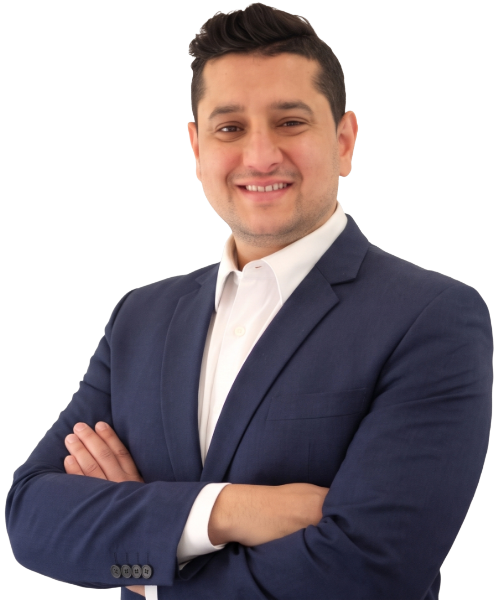
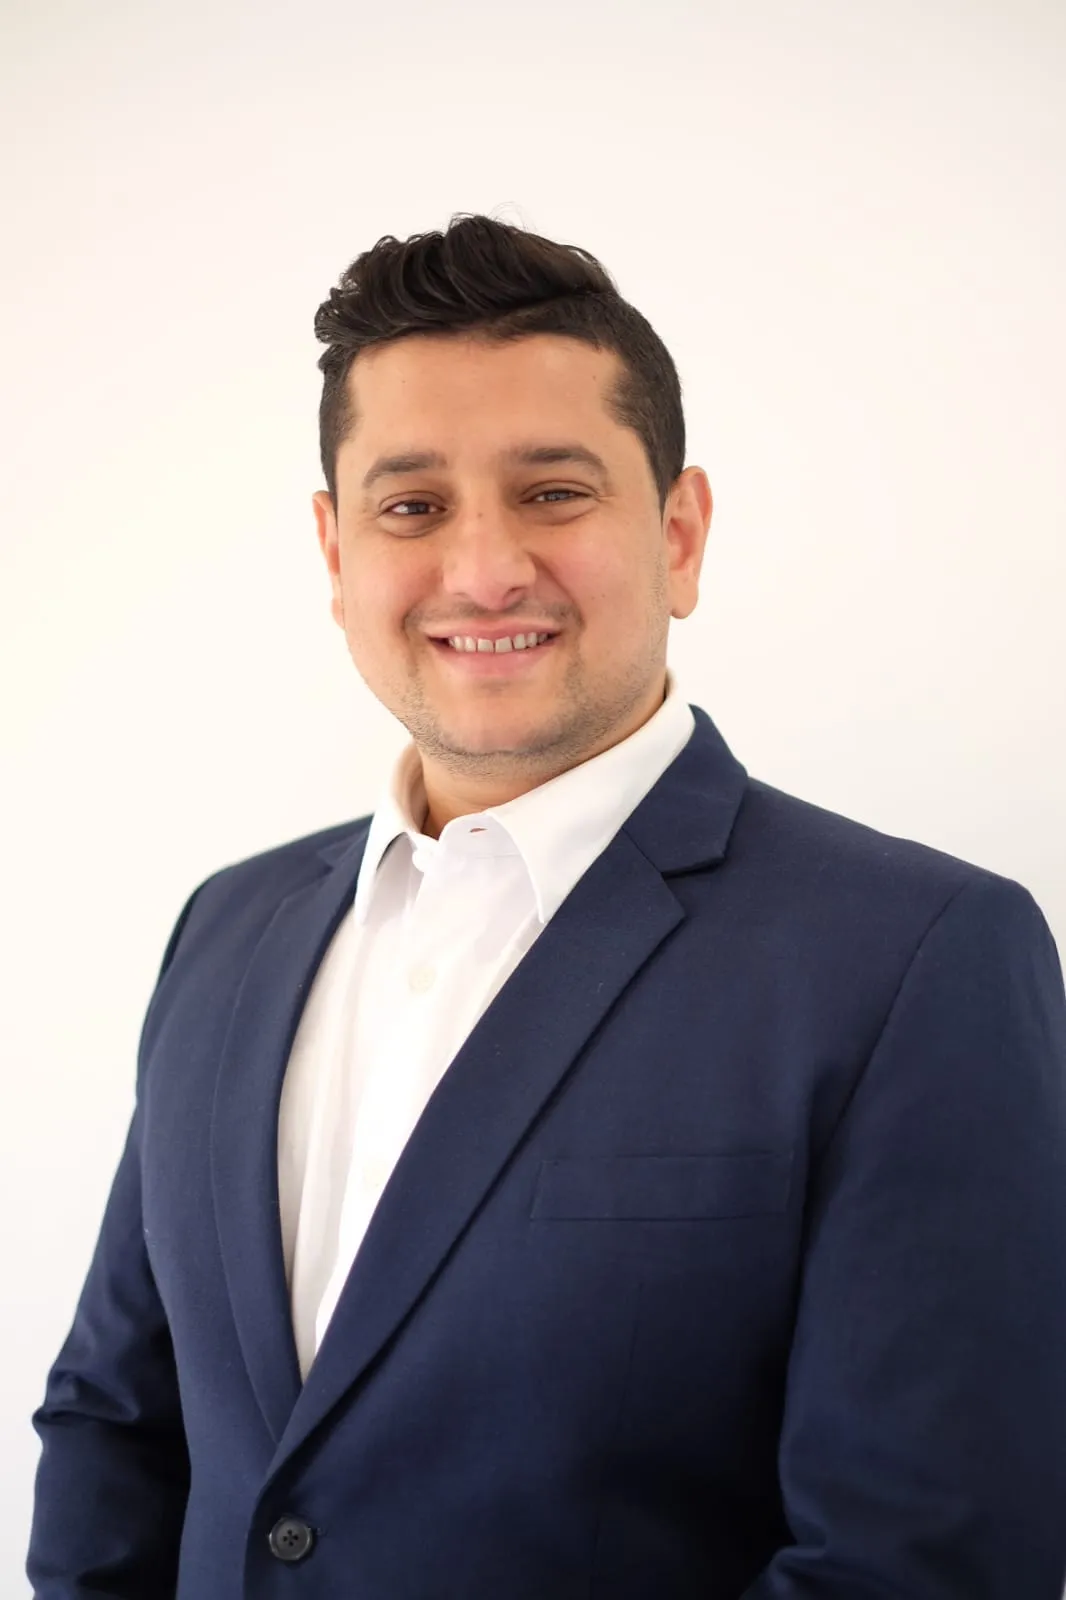
Hi, I'm Mario Reyad From Expert Mortgages
Whether it's your first home, growing an investment portfolio, refinancing, or SMSF property — you don't need another sales pitch, you need someone who'll actually explain it and get results.
We compare your situation across 40+ lenders instead of pushing one bank's shelf, works out what you can genuinely borrow, and handles the process from pre-approval to settlement.
Since starting Expert Mortgages in 2018, the approach hasn't changed: keep it simple, put the client first, and stick around after settlement with regular check-ins — so your loan doesn't quietly go stale.
Straight answers on what you can actually borrow
A genuine comparison across 40+ lenders
Support that doesn't stop at settlement day
Let's Get Started!
Ready To Take the First Step?
Book a free chat with Expert Mortgages and get a clear read on your options
no pressure, no catch.
No obligation to proceed. Lending remains subject to lender criteria, assessment and approval.
Credit Representative 508513 is authorised under Australian Credit License Number 384324 | ABN: 52 625 491 741
Copyright 2026 | Expert Mortgages